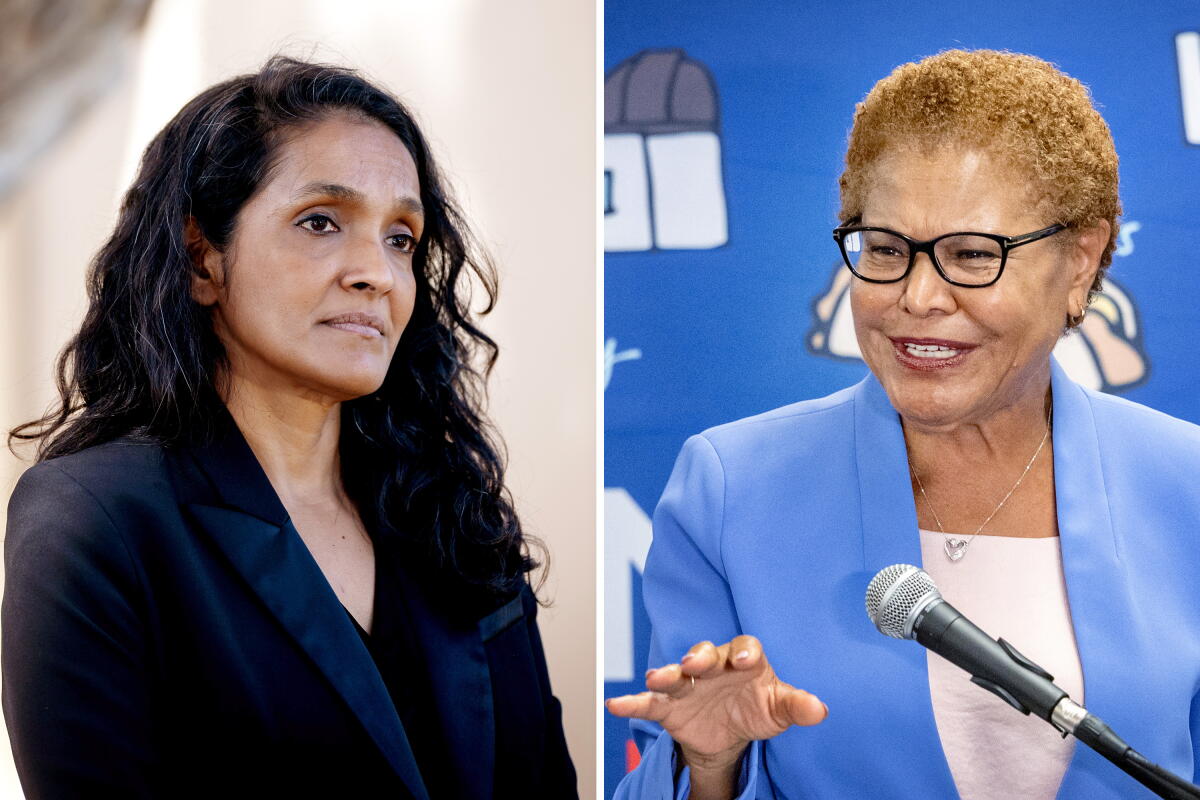
The role of California’s Insurance Commissioner is a critical public office often overshadowed in political discussions. In this election, Democratic candidates Ben Allen and Jane Kim are vying for this position to oversee the California Department of Insurance. This department is the largest state consumer protection agency in the U.S., managing over 1,400 employees.
The Insurance Commissioner is responsible for regulating 1,600 insurance companies and more than 510,000 agents, brokers, adjusters, bail agents, and various business entities. The commissioner’s jurisdiction includes insurance types such as home, car, health, life, pet insurance, worker’s compensation, ride-hailing, and Medicare supplement (Medigap) insurance.
Former Insurance Commissioner Dave Jones, who served from 2011 to 2019, shared insights into the responsibilities associated with the role. He noted that the office impacts voter’s daily lives, influencing areas such as health insurance and worker’s compensation. The commissioner also oversees property insurance rates, with some regulatory limitations. This oversight requires insurers to justify rate increases to the commissioner, an uncommon requirement in most states.
The Underlying Issues Affecting Californians
Jones pointed out that the current affordability crisis in insurance rates is exacerbating financial burdens. Rising property insurance rates trickle down to renters, increasing their living expenses. This situation highlights a fundamental challenge for policyholders and lawmakers.
The California Fair Access to Insurance Requirements (FAIR) Plan provides last-resort fire insurance when traditional coverage is unavailable. In 2019, approximately 190,000 residents relied on this plan. Non-renewals and cancellations of policies contributed to the rising need, with around 235,000 occurrences in the same year. Comparatively, by September, about 686,000 people were on the FAIR plan, indicating a 7% year-over-year increase.
Another alternative insurance option is the Surplus Line Market, which assists when standard options are inadequate or unavailable. While not regulated by the state, it accommodates unique cases like skydiving schools or historical properties. By the end of 2025, a significant number of homeowners found themselves turning to this costlier option.
Challenges and Limitations
Jones mentioned the difficulties faced when insurers choose to exit the state or decline policy renewals. The commissioner can enforce a one-year moratorium on cancellations in wildfire areas but has limited power otherwise. Keeping homeowners insured remains a pressing issue for future commissioners and legislators.
Leave a Reply